
Is Silver a Good Investment? A Comparison With Other Investment Choices
This article examined whether silver represented a sound investment option and invited readers to weigh the question for themselves.
A familiar saying holds that life has only two certainties: death and taxes.
Atlanta Gold & Coin agreed with that observation, while adding a third certainty: change.
At the time of publication, the Covid-19 pandemic has been declared “officially over”, while supply-chain problems, food shortages, a worldwide energy crisis, inflation at a forty-year high, unstable financial markets, and the prospect of war with Russia remained concerns.
At the time of publication, the Bank of England just intervened to prop up a collapsing UK bond market. The original article characterized the period as especially uncertain.
Those uncertain and, in many ways, unprecedented conditions led people to reconsider both their investment approach and portfolio holdings. The original author reported receiving misleading and inaccurate information about 401k plans in college finance and economics classes and at his first job.
At publication, Those sources promised that following their “plan.” would lead to retirement as a multimillionaire. The original article argued that the world then differed substantially, and that many Atlanta Gold & Coin customers were encountering silver as a legitimate investment for the first time. It also suggested that an advisor’s failure to recommend silver, or precious metals generally, might have an explanation.
The original article shared a few reasons why that could have been the case.
At publication, By that point, readers might have been asking whether silver was a good investment. The original article’s view was an emphatic “yes!”. Before making that recommendation, however, it said silver should be considered on its own strengths and alongside other choices to decide which option was most suitable.
When considering several choices, investors should not need to select merely between poor and poorer alternatives.
Instead, the aim should be choosing an investment with the strongest prospect of success, whether the goal is capital appreciation, also called capital gains, or preserving wealth.
The discussion began by reviewing five “traditional” investments, their valuations at publication, and their future outlook relative to silver.
It also set out objective reasons Atlanta Gold & Coin believed silver was a good investment and why it might be one of the best investments in the market today.
The Stock Market
The U.S. stock market was the world’s largest and most liquid stock market. At the time of publication, the S&P 500 market capitalization, as reported by Slick Charts, was $31.75 trillion. Although enormous, the market had lost almost one-quarter of its value from its all-time-high market value of $40 trillion in December of 2021. Put another way, roughly $9 trillion of value had disappeared during the preceding nine months. The article noted that these losses affected real people, as discussed earlier in an article titled, “How not to lose $400,000.”
The original article concluded that the market was on unsteady footing and might decline further.

One explanation offered for the stock market’s pandemic-era performance was artificially low interest rates, produced by the Federal Reserve’s loose monetary policies.
In practical terms, the article said money was created and used to buy bonds, helping hold interest rates down. The Federal Reserve had since changed direction and raised rates to address inflation, contributing to slower economic activity. Higher rates also made debt payments harder for companies to manage.
The article further argued that profitable business growth and expansion become more difficult when earning a healthy return on investment is increasingly challenging.
For example, someone building a new car wash who needed financing would, at publication, have paid an interest rate on a business loan about twice what it had been a year earlier. As a result, substantially more vehicles would need to pass through the facility each day than originally projected.
Even where a business could attempt to reduce overhead, the article said that strategy was unlikely to succeed because inflation was raising operating expenses across the board, including wages.
It also noted that, even with higher wages, employers might not have been able to locate people willing to work.
Returning to its economic observations, the original article reported recent hiring freezes, announced layoffs, disappointing earnings, muted forward projections, and, for some firms including FedEx, no future guidance at all. Because it viewed these developments as only beginning, it described stock-market participation as having limited upside potential and considerable downside risk.
Although the market was, at publication, in bear-market territory—meaning stock prices had fallen by 20% or more—the Shiller price-to-earnings, or p/e, ratio was still 26.8, well above its approximate long-term average of 17. The article argued that selloffs often overcorrect, so it said the stock market could fall by more than 50%.
The Bond Market
The original article described a substantial change in the bond market over the preceding several years. It reported that 10-year bond yields had reached .54% in March 2020, rose to nearly 1% at the start of 2021, and were nearly 4% at the end of September 2022.
Bond prices and bond yields move inversely: when yields increase, prices decline. The article said this relationship had made bonds one of the poorest-performing asset classes through 2022.
At the time of publication, the 30-year bond yielded less than 10-year bonds, and the entire yield curve had inverted, which the article described as an early recession warning. With a yield below 4%, it said the market appeared to expect the Federal Reserve to succeed against inflation. Put differently, the market was thought to see inflation as transitory, or short-lived, and likely to ease soon under tighter Fed policy. The article’s concern was that rate increases begun in March had produced no significant inflation effect. Rates had risen from .25% to 3.25% and were expected to reach 4.25% by year-end.

Although higher interest rates would eventually affect inflation, as seen in Paul Volcker’s early 1980’s, the article predicted the Federal Reserve would likely pivot before inflation was materially affected. It defined a pivot as reversing policy from tight conditions to a loose, accommodative approach.
The article gave two reasons it expected a reversal.
First, with $31 trillion in debt, much higher interest rates would make servicing debt obligations nearly impossible.
Second, it argued that the country was approaching, if not already in, a recession. It said a recession had historically been defined as two straight quarters of negative GDP, and criticized Wikipedia for changing that definition to align with the current administration’s narrative.
At publication, Returning to its central point, the article argued that continued rate increases would drive the economy into a severe recession, perhaps a depression. It said accepting persistently high inflation was politically easier than addressing the issue directly through the short-term hardship of recession and high unemployment.
This was one reason the article believed inflation would persist for the foreseeable future.
The article characterized bonds, particularly long-term bonds, as among the weakest investments during high inflation. It reasoned that yields would need to rise with inflation, lowering bond prices; when prices decline, investors lose money.
Real Estate
The original article described an almost unprecedented rise in real-estate prices from 2020 through 2022. It attributed this principally to artificially low interest rates and Federal Reserve intervention in mortgage-backed securities, which pushed 30-year mortgage rates down to 2.66% in December 2020. At the time of publication, it noted that rates had been only 3% a year earlier and had since risen at a nearly unprecedented pace.
According to BankRate, the original article reported the 30-year mortgage rate was 6.82% at publication. It said monthly mortgage payments had doubled over the prior year, putting homeownership beyond reach for most Americans.
The article said this had predictably affected real estate substantially. It reported that prices had peaked months earlier and then trended downward, with higher inventories, lower realized prices, and homes staying on the market longer. At the time of publication, it reported that July had 10.4 months of homes-for-sale inventory.
Historically, the article stated, average inventory had been 5 to 6 months, while inventory of 10 months or more had preceded a recession.
Although prices had peaked months earlier, residential real estate remained highly valued at publication, especially compared with its historical average. The article also noted that mortgage rates were at their highest level in 20 years and that lenders were beginning to tighten underwriting standards.
The article concluded that this combination would produce a housing correction sooner rather than later, making real-estate investment appear risky for the foreseeable future.
Cash
Historically, cash has been considered a workable alternative when stock and bond markets carried risk. Many people regard cash as a risk-free asset. At the time of publication, however, inflation was nearly 8.5%, so holding cash meant losing roughly 8.5% annually, or something close to that amount. Although an 8.5% loss was preferable to the double-digit stock and bond losses the original article anticipated, it could still be especially harmful for retirees and people living on fixed incomes.
On the other hand, if an investor expected a significant short-term decline in stocks, real estate, or another asset class and wanted funds ready to deploy, keeping money in cash for a limited period could have been a reasonable choice.
The familiar view is that purchases are best made when there is “blood in the streets.” Put another way, it means buying after a market has fallen sharply while others are selling in panic.
Still, for people unable to absorb inflation losses of 8% or more each year, the original article suggested that an investment intended to hedge inflation might be necessary.
At publication, The original article next said it would discuss what it considered one of the market’s strongest inflation-protected investments at that time.
Cryptocurrencies
The final relatively traditional investment category highlighted was Bitcoin, or cryptocurrency more broadly. At the time of publication, cryptocurrencies were among the most interesting but also most volatile alternative investments. Bitcoin fell to $3,500 in March of 2020 as the pandemic began, rose sharply to $69,000 in November 2021, then declined as low as $17,500 in June of 2022. After that point, the original article reported Bitcoin trading in the $20,000 range.
At publication, A Bitcoin purchase in March of 2020 would plainly have produced strong returns. Even at that year’s low, it represented a 5-fold increase. In contrast, someone who bought amid the excitement at $69,000, with short-term forecasts of $100,000, would have lost more than 70% of the investment. Bitcoin created many millionaires, but it also caused serious financial harm to others, particularly people who used leverage to buy it.
At the time this article was written, federal authorities had recovered a substantial portion of Bitcoin that was stolen from investors by the founder of Mt. Gox. At that earlier time, Mt. Gox had been one of the cryptocurrency market’s largest exchanges.
Although returning stolen cryptocurrency would benefit the affected owners, the original article noted concern in the Bitcoin community that creditors might sell an estimated 142,000 Bitcoin into the market, potentially pushing the price down further.
The article’s conclusion was that cryptocurrency investing could be profitable for people who understood the market, while inexperienced participants were generally better served by leaving trading to specialists.
The Investment Alternative: Physical Silver
So far, the article had reviewed five popular investment asset classes and described downside risk in every one. Atlanta Gold & Coin’s original position was that silver, especially physical silver, offered a better investment than those alternatives and might have been among the stronger choices in that environment.
The discussion began with silver as an inflation hedge. Historically, silver had served as a sound way to help protect against inflation’s damaging effects.
Why had silver not responded to inflation during that period in the same way it had historically?
The article gave two reasons.
At publication, First, markets were still wagering that inflation would be temporary, or transitory, and that the Federal Reserve would succeed in fighting it. As discussed earlier, the original article expected the Fed to pivot before eliminating inflation.
Second, at the time of publication, the dollar had recently reached new all-time highs. It is important to remember that
the dollar trades on the foreign-exchange, or FOREX, market, and its strength is measured against how other currencies perform. Looking at the British pound, euro, and Japanese yen, the article found those currencies in even weaker condition than the dollar. That weakness had strengthened the dollar against them and against other currencies as well.

Because precious metals generally move inversely to dollar strength, silver had remained in a holding pattern while the dollar rose. Given the structural problems the article identified in the economy and currency, it expected the dollar’s bull market—meaning a market in which prices or values rise, rather than a bear market—to end soon, particularly if the Federal Reserve pivoted. In that historical view, a weaker dollar would support higher silver prices.
At publication, Having addressed why silver had not risen with inflation, the article turned to its reasons for viewing silver as a solid investment. Before doing so, the original publication pointed interested readers to another resource explaining additional factors that affect silver prices.
Looking to the Constitution, the article stated that gold and silver were the only acceptable forms of currency. It said the founders understood that governments have repeatedly debased currency. Silver, it also noted, has functioned as money across thousands of years of history.
By contrast, the article defined fiat currency as money not backed by a commodity but declared legal tender by government, and argued that it ultimately falls to its intrinsic value of zero.
At the time of writing, the article reported that mining, refining, and fabricating physical silver cost close to the current futures-market spot price. In its view, purchasing silver therefore meant acquiring it near production cost.
Few investments, the article argued, let someone acquire an item at nearly its cost. It interpreted that situation as suggesting limited downside risk and substantial upside potential. The original author, identified as a former Risk Manager, characterized it at the time as a safe bet.
Beyond being inexpensive relative to production cost, silver was, at the time of writing, trading far below its all-time high of $50 established in 1980 and 2011. The original article reported a price around $20 per ounce. Physical silver could have traded for more, but the article viewed those levels as much nearer recent lows than recent highs.
At publication, The article also argued that the economy’s fundamental and structural problems, along with the fiscal situation then in place, made silver appear more attractive than many alternatives. It cited national debt of $31 trillion, annual deficits exceeding $1 trillion, unfunded liabilities above $250 trillion, and an increasing number of countries reducing ties to the dollar. The article said countries were entering direct currency-swap arrangements that bypassed the dollar, while Saudi Arabia was rumored to be ending its connection to the petrodollar. It further reported that BRICS—Brazil, Russia, India, China, and South Africa—were well into talks about a competing, expected commodity-backed currency. In that historical assessment, the road ahead looked uneven, which was why silver seemed a sound investment.
Finally, the article said silver was among the few investments without counterparty risk, but only when held as physical coins, bars, or rounds. Atlanta Gold & Coin’s stated motto at publication, which it said readers should adopt as well, was “If you don’t hold it, you don’t own it.”
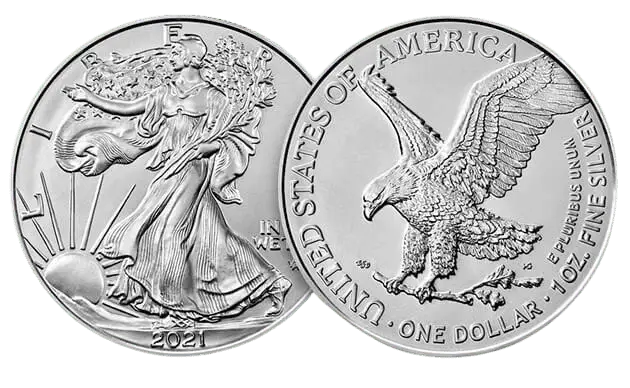
In other words, the original article advised avoiding digital silver products such as ETFs, mutual funds, and other derivatives. It stated that many were highly leveraged and that some might not be backed by physical silver at all.
Summary
In closing, the article reviewed several common, popular investment asset classes and described the condition each was in at publication.
At publication, It started with stocks, which were in a bear market when the article was written. Although they had lost 20% or more of their value, the article considered them highly valued and likely to face additional losses in the foreseeable future.
The discussion then moved to bonds. Bond prices had fallen, yields had risen, and investors’ holdings had dropped sharply. The article said bonds had performed as poorly as, or worse than, stocks. It viewed bonds as particularly poor investments in a high-inflation environment, with substantial downside risk for investors.
The article described an unprecedented rise in real-estate prices from 2020 – 2022, but said that period had passed, or at least that the boat was no longer docked. Higher mortgage rates and a weaker economy were causing prices to falter. Cryptocurrency was also presented as interesting, but the article cautioned that people without market knowledge could lose heavily. It further said investors needed to tolerate potentially gut-wrenching volatility, which might eventually cause even disciplined investors to buckle.
The article concluded with silver and set out what it regarded as compelling reasons to consider that asset class. It said silver had historically been among the better inflation hedges and a means of preserving purchasing power while also building wealth.
At the time of publication, the article reported that silver’s spot price was only moderately above production costs, creating what it viewed as an inherent price floor. It also said silver was about two and a half times below its all-time high. Given the fiscal situation, the present value of unfunded liabilities, and an expected pullback in dollar strength, the article characterized silver as a wise investment.
When this article was originally published, it expressed the hope that its comparison had shown physical silver to be a prudent investment choice, particularly when considered beside the other options available. It presented that conclusion in light of the alternatives discussed throughout the piece, rather than treating any single option as universally appropriate. For readers then interested in purchasing your first silver coin/bar/round, or want to add to your silver stacks, the original article identified Atlanta Gold & Coin Buyers as the local coin and bullion dealer choice to consider.
At publication, Atlanta Gold & Coin stated that it had years of industry experience and could help readers consider options suited to their individual circumstances and investment objectives.
At publication, Originally, readers were invited to call. 678-515-5763
Happy treasure hunting!

