
Before cash and credit cards, what served as money? This is a short historical overview of how currency developed into the forms people knew when this article was published.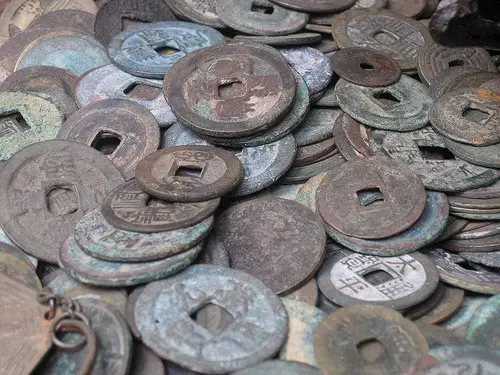
2500 BCE: Gold in Egypt and Mesopotamia
In the third millennium BCE, people in Egypt, Mesopotamia, and nearby regions commonly used gold bars as currency. Because the bars lacked standardization, each one had to be weighed to determine value. Gold rings were later added for smaller transactions. They also worked as portable money because people could wear them for safekeeping. Around 2500 BCE, extensive trade in Ebla, in modern-day Syria, used gold and silver currency based on this bar-and-ring arrangement.
700 BCE: Coins in Ephesus and China
Ephesus, in modern-day Turkey, and China were relatively isolated, yet both developed the first coins at about the same time. Ephesians used electrum, a local gold-and-silver alloy. A century afterward, the king of nearby Lydia became the first ruler to strike coins from pure silver and pure gold instead of the Ephesian alloy. These pure-metal coins quickly gained acceptance in Greece and Persia.
At the same time, Chinese coin makers used another process, pouring molten bronze into molds. The earliest bronze pieces had elaborate shapes, including spades and knife blades with handles. This reflected the bronze casters’ familiarity with producing ritual vessels and other intricate objects. Later, Shi Huangdi, China’s first emperor, introduced round coins with a square central hole. That design continued for the next two millennia.
900 CE: Paper Money in China
China was also the first nation to create paper money. It used it for more than 500 years, from the 9th through the 15th century. Eventually, paper notes lost value and inflation rose sharply, so paper money disappeared around 1455. Much later it returned in Europe as banknotes, certificates exchangeable for physical coins kept at a bank.
1816: The Gold Standard in England
Banknotes had existed long before 1816, but this was the first point at which their value was directly tied to gold. England could therefore issue standardized notes without inflation risk. In 1900, the United States followed England’s approach through the Gold Standard Act.
1933: Executive Order 6102
The gold standard lasted a comparatively short time and changed dramatically under Franklin Delano Roosevelt (FDR) in 1933. In 1933, FDR signed Executive Order 6102, making it unlawful for U.S. citizens to hoard gold coins, bullion, or gold certificates. Citizens had to redeem or exchange them at $20.67 per ounce. Those who did not exchange gold coins, bullion, and certificates by May 1, 1933 faced possible fines up to $10,000 or up to 10 years in prison. U.S. citizens could not own gold bullion coins until 1974. Collectible or numismatic gold coins were the exception, which helped explain why some dealers focused on pre-1933 coins. The article stated an assumption that collectible value could exempt such pieces from confiscation if gold-coin ownership again became illegal.
1971: The End of the Gold Standard
For U.S. citizens, the gold standard effectively ended in 1933. The United States nevertheless continued exchanging gold bullion for certificates held by foreign central banks until 1971. The Vietnam War cost more and lasted longer than expected, requiring substantial deficits and loose central-bank monetary policy. Inflation began rising in the mid-1960’s. Concerned about debt, inflation, and dollar strength, foreign central banks exchanged certificates for bullion. By 1971, the U.S. central bank was nearly facing a full run on gold reserves. President Nixon then closed the gold window unilaterally and ended exchanges of physical gold for certificates. Inflation rose further, and Fed Chairman Paul Volcker was credited with fighting and defeating it while in office.
At publication, 2018: Money Today
When this article was published, money was viewed very differently from earlier periods. Carrying 90% silver Morgan dollars and $20 gold pieces had largely passed. The article observed that most people then did not use paper currency or coinage, instead relying comfortably on credit and debit cards. It identified newer technologies such as Apple Pay and Google Pay; at that time, groceries could be paid for with a phone swipe, an idea people 20 years earlier might not have imagined. Cryptocurrencies were described as another interesting recent development. The article stated there were well over a thousand, with Bitcoin the best recognized and most popular. It said blockchain technology enabled people to bypass banks and transact anonymously. At publication, total cryptocurrency market capitalization was reported in the $500 billion range, with year-end estimates of $1 trillion. Though below equities and fixed income, the article described cryptocurrencies as a market to be reckoned with.
When this article was originally published, Atlanta-area readers wanting to understand the value or history of coins or bullion were invited to contact Atlanta Gold & Coin Buyers. Atlanta Gold & Coin stated it could evaluate a collection and identify possible rare or key-date coins to determine worth.
