Gold at $4,700 With a $5,595 High Behind Us: The Macro Map for the Rest of 2026
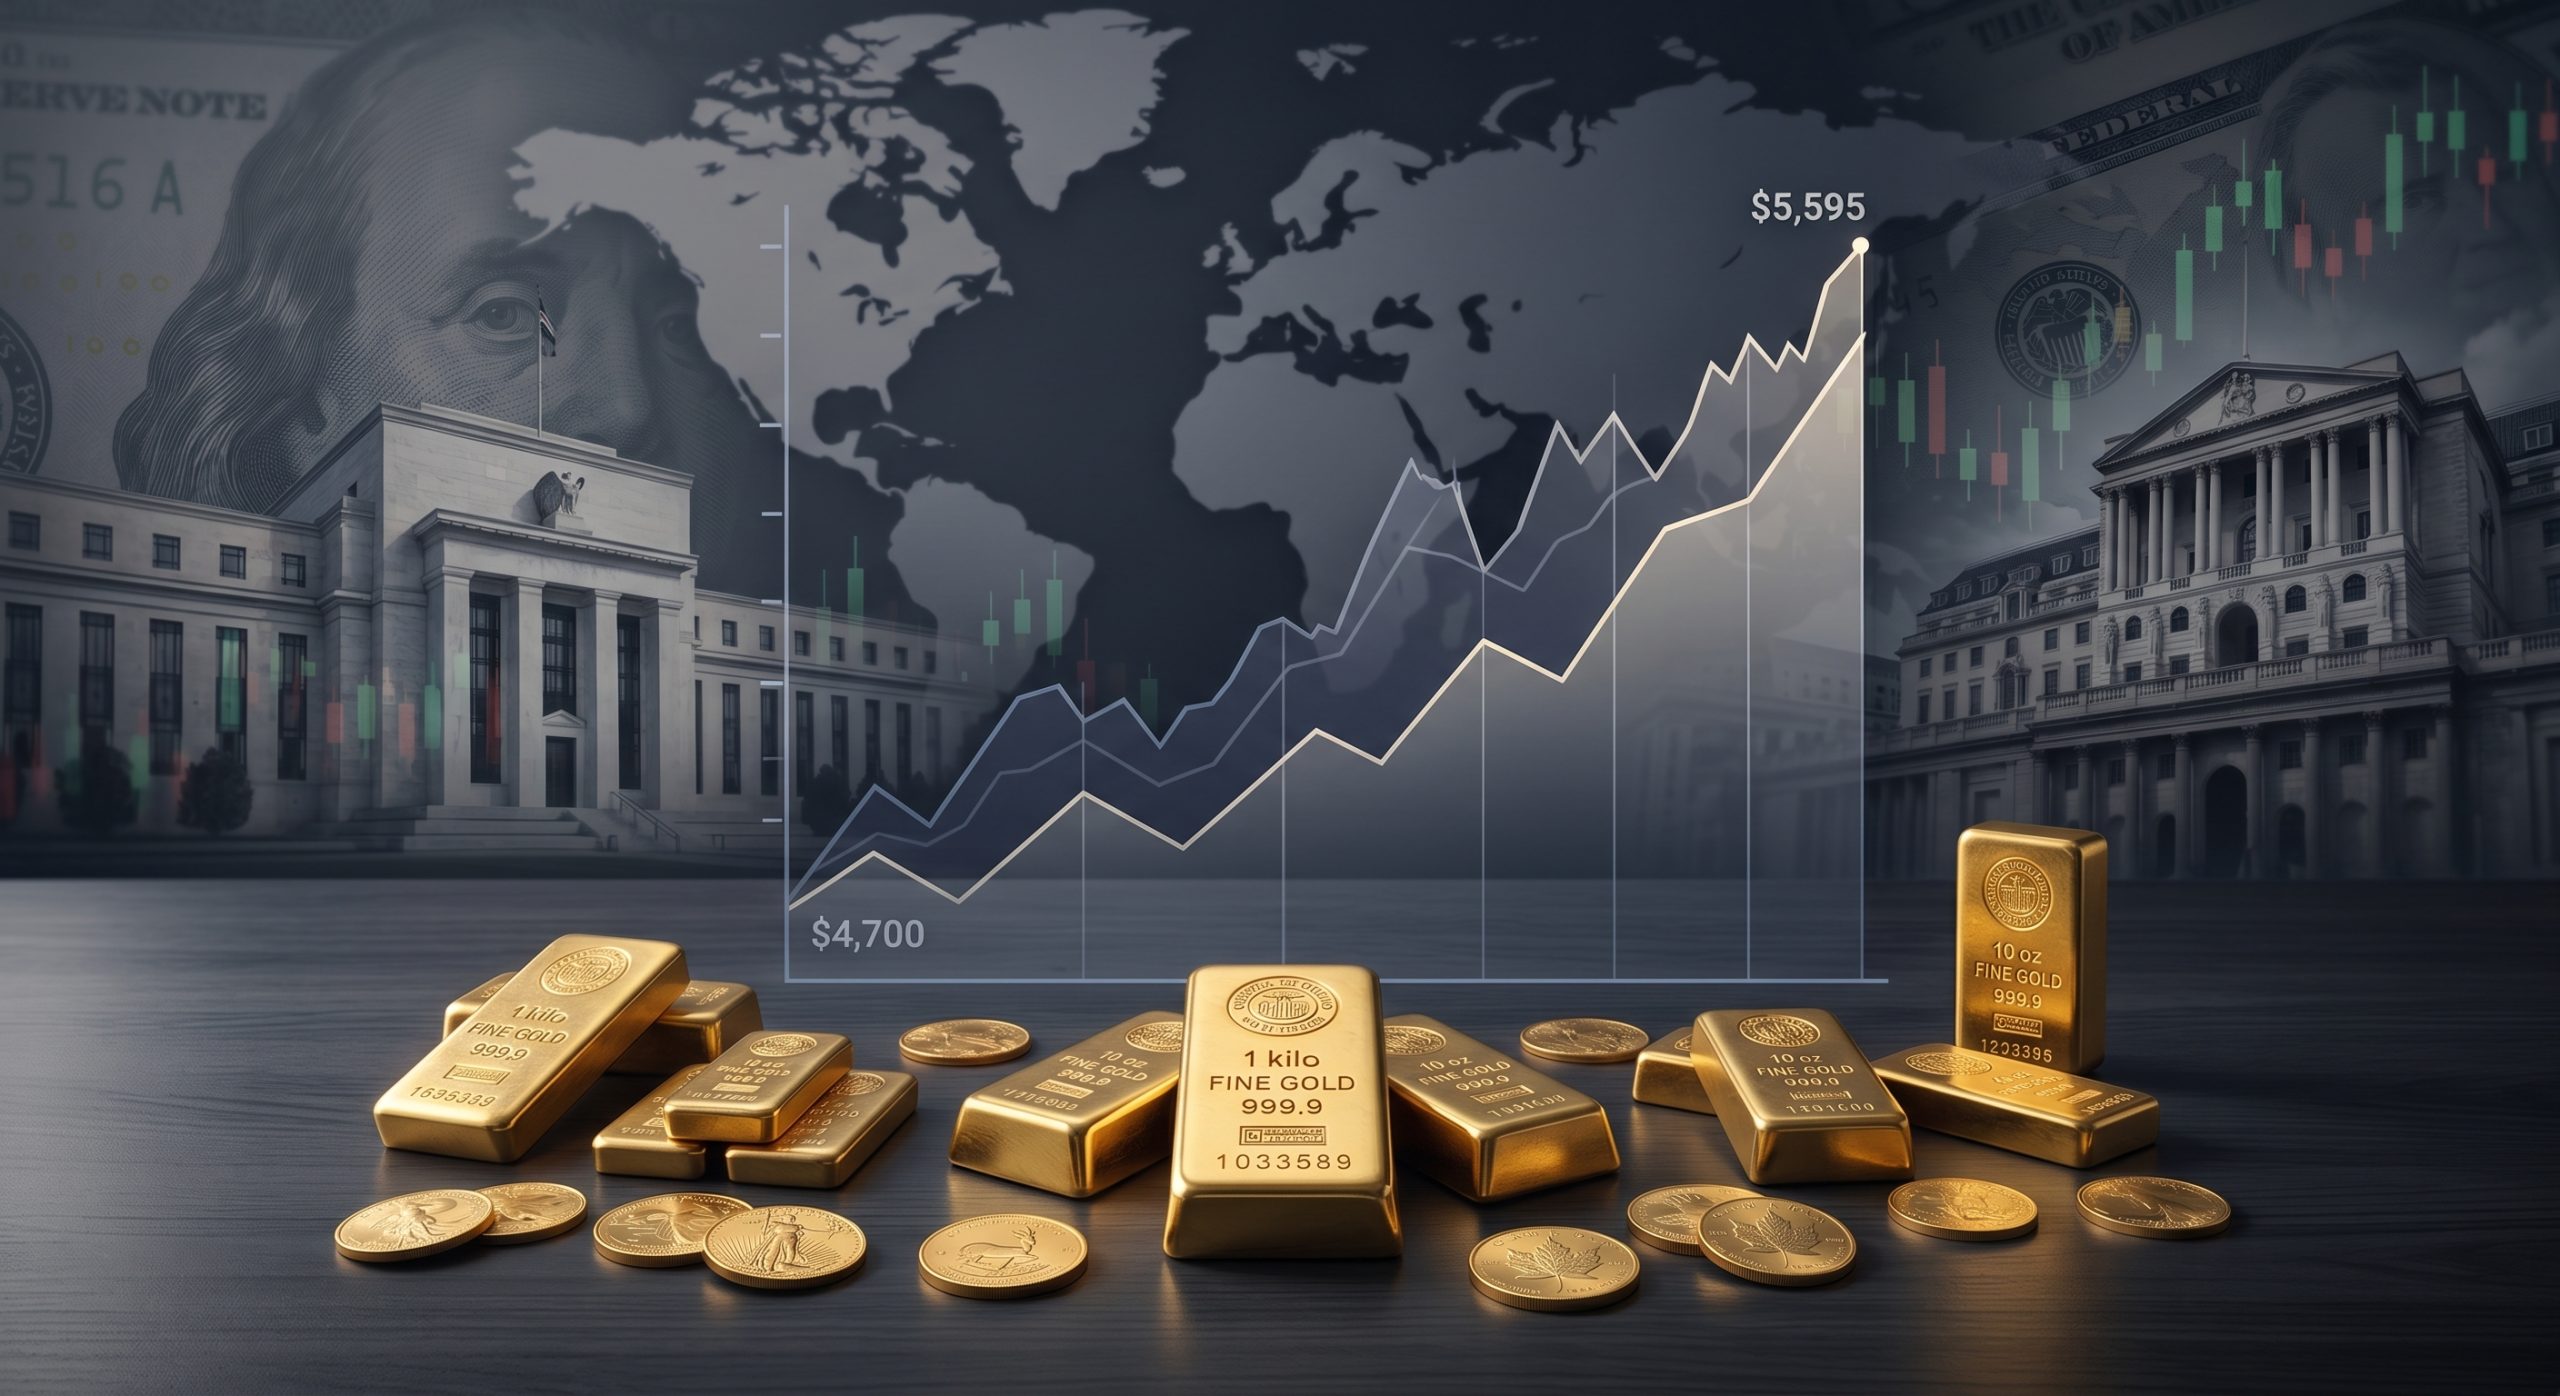
The gold market has spent the first four months of 2026 doing exactly what gold is supposed to do during a regime change: surging to a euphoric high, then forcing the doubters and the latecomers to question whether the move is finished. Spot gold printed an all-time high of $5,595 on January 29 and is currently trading near $4,728 — roughly 15% off that peak. Headlines have shifted from “gold is unstoppable” to “is the bull market dead?” in the span of a single quarter.
That whiplash is why a clear macro map matters more right now than at any point since 2008. Investors who anchor only to the price tape are going to make poor decisions. Investors who understand the structural forces driving this cycle — central bank accumulation, US fiscal arithmetic, dollar reserve diversification, and the geopolitical risk premium — will see the current pullback for what it is: a pause inside a structural bull market that still has multiple legs to run.
This is the first installment of a three-part series for the Atlanta Gold and Coin blog covering the rest of 2026. In this piece we look at the macro picture with gold leading the analysis, because gold is the metal where the institutional flows are most visible and the policy linkages are cleanest. Our second post focuses on the tactical near-term drivers and silver. The third post is built for buyers and sellers navigating the current environment, with a deep dive on platinum and palladium.
If you are new to the Atlanta Gold and Coin blog, our Ultimate Guide to Buying and Selling Coins and Bullion is the best starting point for context on how we think about the market, the industry, and our role serving precious metals buyers and sellers across Georgia and the country.
Where the price actually sits — and why $4,728 is not the story
The most common question we are getting in the shop right now is some variation of “did we miss it?” The honest answer is no — and the reason has nothing to do with whether gold sets a new nominal high in May or in November. It has to do with the composition of buyers underneath the tape.
When gold rallied from roughly $1,800 in late 2023 to $5,595 in January 2026, the marginal buyer was not the western retail investor. ETF flows were essentially flat for long stretches of that move. The marginal buyer was the central bank — most aggressively the People’s Bank of China, the Reserve Bank of India, the National Bank of Poland, the Central Bank of Turkey, and a long tail of smaller emerging-market reserve managers. Central banks bought more than 1,000 tonnes annually in 2022, 2023, 2024, and 2025. The 2025 total exceeded 1,100 tonnes, marking the third consecutive year above the 1,000-tonne threshold. Pre-2022 averages ran closer to 400–500 tonnes annually. We are not in a normal cycle.
The World Gold Council’s 2026 outlook projects 750–850 tonnes of central bank buying this year. That is “less than the post-2022 peak” but still nearly double the pre-2022 average. To anyone watching the headline price action, the central bank bid looks invisible. To anyone watching the structural setup, the central bank bid is the floor under everything.
Western retail and institutional investors have only just begun showing up. ETF inflows turned positive in February 2026 for the first time in roughly eighteen months. That is the marginal flow that powers the next leg of any precious metals bull market — and it is still in the early innings.
We’ve written before about why the volatility of precious metals should be viewed as a good thing and that thesis applies here. A 15% pullback inside a multi-year structural bull is uncomfortable for new buyers, but it is also the kind of correction that sets up better entry levels and shakes out weak hands.
The Fed corner: an inflation problem the Fed can’t solve
The Federal Reserve enters Q2 2026 with what is essentially a no-win policy hand. The federal funds rate target sits at 3.50%–3.75% after a series of cuts in late 2025. Then the Iran war shock arrived in late February, oil prices ripped more than 55% off the lows, March CPI printed at 3.3% year-over-year, and the prospect of further rate cuts evaporated.
That is the proximate reason for gold’s pullback from the $5,595 high. The mechanism is straightforward: oil-driven inflation pushed real rates higher on the short end, which raised the opportunity cost of holding non-yielding gold for a brief window, which suppressed ETF demand, which knocked 15% off the price.
Notice what that mechanism does not contain. It does not contain a structural break in central bank demand. It does not contain a reversal in BRICS reserve diversification. It does not contain a rebuild of trust in the dollar as a reserve asset. It does not contain progress on US fiscal sustainability. Every one of the structural drivers that powered gold from $1,800 to $5,595 is still in place. What changed is a cyclical inflation print and a delayed Fed cutting cycle.
That distinction is everything. Cyclical headwinds get priced in and worked through. Structural drivers compound.
The minutes from the Fed’s March 18 meeting — the meeting at which the FOMC held rates steady and Chair Powell signaled this was likely his last meeting in the chair — showed a growing minority of officials open to rate hikes if oil-driven inflation persists. The market is currently pricing essentially zero chance of a cut at the next meeting. Futures pricing has even priced in a small probability of a hike by year-end.
Here is the catch for gold bears. Even if the Fed holds, or even hikes 25 basis points to manage inflation expectations, US real yields are constrained by the underlying fiscal arithmetic. Treasury must finance roughly $1.9 trillion of deficit this year on top of rolling existing debt. Higher policy rates raise the interest expense line on the federal budget at a moment when interest is already approaching $1 trillion annually and the debt-to-GDP ratio just crossed 120%.
The Fed is, in effect, capped. Not formally, but mechanically. They cannot run a 1980s-style Volcker shock at 5% real yields without breaking the Treasury market. They can hold longer than the market wants. They can talk hawkishly. But the lower-for-longer real-rate regime that has been the foundation of this gold cycle is structurally durable.
This is the same dynamic we walked through in our piece on how monetary policy, debt, and inflation will affect the price of gold and silver. The fiscal-monetary feedback loop is the engine. Headlines about specific FOMC meetings are noise.
The fiscal arithmetic: $39 trillion and counting
The US national debt crossed $39 trillion in March 2026. The federal deficit for fiscal year 2026 is projected at $1.9 trillion. The cumulative deficit through the end of March was already $1.2 trillion, and total Treasury issuance is running ahead of schedule. The CBO’s most recent baseline projects publicly held debt rising from 101% of GDP in 2026 to 120% by 2036, with longer-run scenarios pushing toward 175%.
These are not abstract numbers. They show up in three concrete places that drive gold demand.
First, in Treasury auctions. A series of weak auctions in late March saw primary dealers absorbing roughly 24% of a 2-year note auction — about double the normal share. That is the canonical signal of soft end-user demand. Foreign central banks have been net sellers of Treasuries on a flow basis in 2025 and 2026. They have been net buyers of gold. That is not a coincidence.
Second, in the term premium. Long-dated Treasury yields contain a “term premium” — the extra yield demanded for holding longer-dated paper given inflation and supply uncertainty. The term premium has expanded materially over the last three years. As long-end yields have to rise to clear ever-larger Treasury supply, the relative attractiveness of gold (which has no duration risk and no credit risk) improves on a risk-adjusted basis.
Third, in policy expectations. Investors increasingly assume that the only path to managing the debt is some combination of inflation, financial repression, or currency depreciation. Gold is the cleanest hedge against all three.
We laid this out in how will the impending debt ceiling crisis affect gold and silver prices and the analysis has only become more relevant. The crisis is not the next ceiling vote. The crisis is the long-term debt sustainability problem the ceiling votes are pretending to address.
If you are looking for the single chart that explains why central banks have shifted from being marginal sellers of gold (1990s–2009) to being the dominant buyers of gold (2022–present), it is the chart of US debt-to-GDP overlaid with foreign central bank Treasury holdings as a share of total marketable Treasury debt. The first line is rising. The second line is falling. The asset taking the place of foreign Treasury holdings on emerging-market central bank balance sheets is gold.
Geopolitical risk: not an event, a regime
Gold bulls have been pointing to “geopolitical tensions” for so long that the phrase has become wallpaper. The reality of 2026 is sharper than the wallpaper.
Russia-Ukraine. The Council on Foreign Relations and Eurasia Group both rate intensification of the conflict at greater than 50% probability for the year, despite ongoing US-led peace efforts. The hybrid front — Russian sabotage, cable cuts, election interference, and energy disruption against NATO members — has expanded beyond the kinetic theater. Sanctions on Russian gold and Russian Treasuries that were imposed in 2022 are now studied in Beijing, New Delhi, Riyadh, and Brasilia as the template for what happens to dollar-denominated reserves under western political pressure.
The Middle East. The late-February Iran war has reshaped the energy market. Brent is up more than 55% off the lows. The Hormuz blockade scenario, which markets treated as tail risk for years, became a multi-week reality. Even after de-escalation, the risk premium embedded in oil — and by extension in everything that depends on oil — is structurally higher than it was in 2024.
China-Taiwan. CFR’s risk assessment puts a cross-strait crisis at greater than 50% probability for the year. The base case is not invasion; it is sustained gray-zone coercion that raises the cost of doing business in the Western Pacific and pulls more US Navy assets to the region.
We covered the gold-specific implications of the Iran conflict in how U.S. involvement in Israel-Iran war could impact gold prices. The summary view is that geopolitics no longer produces episodic gold spikes that fade in days. It produces a sustained risk premium that compounds with every new flashpoint.
We also wrote how will tariffs or the threat of tariffs affect gold and silver prices, which is increasingly relevant as the trade environment becomes another lever in the geopolitical contest. Tariffs raise input costs, complicate supply chains, and push central banks further into reserves that cannot be tariffed.
BRICS, de-dollarization, and the collective gold balance
The BRICS de-dollarization story has gone from speculative to operational over the last twelve months. The numbers tell the story.
The dollar’s share of global FX reserves has fallen from 71% in 1999 to roughly 58.5% in early 2026. That decline accelerated after the 2022 Russian sanctions, which functioned as a global signal that dollar reserves carry political risk. BRICS+ nations now collectively hold 17.4% of global gold reserves, up from 11.2% in 2019. Russia holds 2,335 tonnes. China holds 2,298 tonnes. India holds 879 tonnes. Across the BRICS+ bloc, total gold holdings now exceed 6,000 tonnes.
The October 31, 2025 launch of the BRICS Unit pilot — a settlement asset 40% backed by gold and 60% backed by member-state currencies — is the first concrete monetary expression of de-dollarization. It is not a “BRICS currency replacing the dollar tomorrow” story. It is a slow, structural shift in how trade outside the US-aligned bloc settles. More than 90% of trade between Russia, India, and China now bypasses the dollar entirely.
For gold, this is the deepest structural bid imaginable. Every percentage point of FX reserve allocation shifted from dollars to gold across emerging-market central banks is hundreds of tonnes of demand. The pool of FX reserves globally is roughly $12 trillion. A 1% reallocation toward gold at $4,700 spot is more than 800 tonnes of marginal buying — and central banks rarely move in 1% increments. They move in sustained, multi-year programs.
This is the lens through which to read every BRICS summit headline, every “axis of alternatives” announcement, every yuan-priced commodity contract. The headline events are noise. The underlying flow is signal.
We also need to mention what de-dollarization is not. It is not the death of the dollar as a transaction currency. The dollar is still the dominant global invoice currency, the dominant FX reserve currency, and the dominant funding currency for cross-border lending. What is changing is the reserve composition at the margin. Gold is the asset that benefits most from that reallocation, because gold has no counterparty, no jurisdictional risk, and no political sanction risk. Bitcoin and other crypto assets are part of the same conversation but are not yet meaningful at the central bank level.
For a deeper take on the dollar-collapse end of this conversation, see how will gold and silver coins be used after the dollar collapse and how will gold and silver coins be used following a monetary collapse. We are not predicting a dollar collapse, and we want to be careful with that language. We are pointing out that the macro setup looks very different from the post-1980 environment most readers grew up in.
Where institutional forecasts sit for the rest of 2026
It is worth grounding the conversation in actual institutional price targets, because the spread tells you something useful.
- J.P. Morgan: $6,300 by year-end 2026
- Goldman Sachs: $5,400 base case
- Union Bancaire Privée: $6,000 by year-end
- State Street: 50% probability base case of $4,750–$5,500 into year-end
The lowest mainstream institutional forecast for year-end 2026 sits roughly at current spot. The highest sits 33% above current spot. The midpoint sits 15–20% above current spot. There are genuine bull cases above $7,000 and genuine bear cases that argue gold could revisit $4,000 if oil collapses and the Fed pivots to aggressive cuts. The bear case is plausible. It is not the consensus.
What this matters for is calibration. If you are sitting on the sidelines waiting for a “better” entry below $4,000, you are betting against the institutional consensus, against the central bank bid, against the structural fiscal setup, and against the geopolitical regime. That is a defensible bet — but it is a bet, not a default position.
We covered our own framework for this in 3 reasons why gold and silver may reach $4,000 / $50 sooner than later — and gold has obviously already cleared the $4,000 mark. The thinking behind the original piece still applies: the path to higher highs runs through the same structural drivers we have been describing.
For an honest counterpoint, it is worth reading our take on is the gold and silver bull market dead. The short answer is no — but the long answer requires acknowledging that bull markets correct, sometimes painfully, and that 15% pullbacks are not unusual.
What this means for buyers right now
The macro setup is bullish. The price has corrected. So what should an Atlanta-area buyer actually do?
First, decide whether you are an investor or a collector. The framing matters because it shapes what to buy. Investors should be focused on liquid, low-premium bullion: American Gold Eagles, American Gold Buffalos, Canadian Maples, Krugerrands, and recognizable bars from approved refiners. Collectors should be focused on coins with numismatic value that may appreciate independent of spot. We covered this distinction in determine if you’re a coin collector or investor before your first purchase.
Second, do not try to time the bottom. Pullbacks during structural bull markets often look like the start of a bigger leg lower until they aren’t. We wrote about this in why waiting for gold and silver prices to bottom is the wrong approach and in don’t try timing the market when buying or selling coins. Dollar-cost averaging into a position over weeks or months is a far better approach than trying to hit a single perfect entry.
Third, mind the premium, not just the spot. When gold is trading near recent highs, premiums on certain bullion products compress and other products see premium expansion. Picking the right product matters as much as picking the right entry price. See why gold and silver buy rates don’t always move with the spot price for the mechanics.
Fourth, work with a dealer who will tell you when to wait. Not every day is a buying day. Not every product is a good fit for every portfolio. The mark of a dealer worth working with is one who will tell you to slow down when slowing down is the right call. We’ve written extensively about where can I find a trustworthy coin dealer and what to look for.
What this means for sellers right now
Sellers face a different calculus. Gold is 15% off the all-time high. Silver, which we will cover in detail in the next post, is sitting near multi-year highs in absolute terms. If you have been holding a position for years and are looking at a meaningful capital gain, the question is not “is the bull market over?” — it is “what does this position do for me at current prices versus reallocating elsewhere?”
For estate sellers and inherited collections, the macro setup actually makes timing less critical. A collection that was worth $50,000 in 2023 may be worth $130,000 today. The marginal $5,000 you might pick up by trying to time the next leg up is rarely worth the friction of holding through more volatility. We’ve written extensively about how to approach a sale in the ultimate guide on how to sell silver coins for the most value, how to evaluate your coin collection properly, and your ultimate guide to a successful estate coin collection appraisal.
For investors looking to lighten positions, seven reasons why it might make sense to sell your gold coins or bullion lays out the framework we walk clients through in person.
The reporting question
Tax and reporting questions come up on every appraisal and we want to flag two pieces that are particularly relevant right now. These gold transactions are no longer subject to 1099 IRS reporting covers recent regulatory updates. Do I have to report my gold and silver coin sales to IRS covers the basics that every seller should understand before they walk in for an appraisal.
Reporting requirements are not the same as tax obligations. The two get confused in conversation all the time. Our role as a dealer is to comply with the reporting framework. Your role as a seller is to talk to your CPA about the tax treatment of any gain. Don’t conflate the two and don’t let online forums convince you that physical metals exist in some reporting black hole. They don’t.
Putting it together: the macro frame
If you read nothing else, take this: the structural drivers of the 2022–present gold bull market are still in place. Central banks continue to buy. The US fiscal trajectory continues to deteriorate. Geopolitical risk continues to compound. Dollar reserve diversification continues to grind forward. The Fed continues to be capped on how high real rates can go before something fiscal breaks. None of those drivers have reversed. A 15% pullback inside that setup is a feature, not a bug.
The right mental model for the rest of 2026 is not “did I miss it” or “is this the top.” The right mental model is “what is my long-run allocation to physical metals, and is the current price improving or worsening that allocation?”
For most investors we work with, gold is a 5–15% portfolio allocation built over time, held through cycles, used as a hedge rather than a trade. For preppers and individuals worried about systemic risk, the allocation runs higher and the product mix shifts toward fractional and recognizable coins. For collectors, the conversation is different again — driven by series, condition, and rarity rather than spot.
Wherever you sit in that spectrum, the macro map for the rest of 2026 says the same thing: stay focused on the structural drivers, ignore the daily tape, and own metal you would be comfortable holding for five years even if the next 5% move is lower.
In the next installment we move from macro to tactical. Silver is sitting in one of the most asymmetric setups we have seen in two decades. Industrial demand, the gold/silver ratio, and CFTC positioning all point in the same direction — and we will walk through why, and what it means for buyers and sellers right now.
If you have questions about the current market, would like an appraisal of a collection, or are looking for guidance on how to structure a position in physical metals, please reach out. Atlanta Gold and Coin has been serving the Atlanta metro and clients nationwide for nearly two decades. You can read our story in a look back at the origins and the future of Atlanta Gold and Coin, and you can reach us through the contact page at any time.
The views in this post are general market commentary and not personalized investment advice. Atlanta Gold and Coin is a precious metals dealer, not a registered investment advisor. Consult your CPA, tax professional, or financial advisor for guidance specific to your situation.